
AlphaTrack – SPX500 Breaks Key Support as Bearish Momentum Builds

Thoughtful insights and approachable analysis.
- Apple delivers record earnings, yet its shares stumble. Can the bulls reclaim $345, or is a deeper correction looming?
- AMD faces an earnings showdown at $435. Will AI optimism fuel a rebound, or will the bears tighten their grip?
- Qualcomm tumbles ahead of earnings. Will results revive the bulls, or send shares tumbling towards $140?
Quick Market Overview
US stocks suffered a sharp intraday reversal as investors turned cautious ahead of the midterm elections and another heavy week of earnings. For markets, the key support remains corporate profit growth, but confidence is increasingly tied to whether AI spending continues at current levels. With much of the good news already priced in, any sign that major technology companies are cutting capital expenditure could hit the broader indices hard, while strong earnings and a smooth Anthropic IPO would help stabilise sentiment.
General Equity Market Health (SPX500)
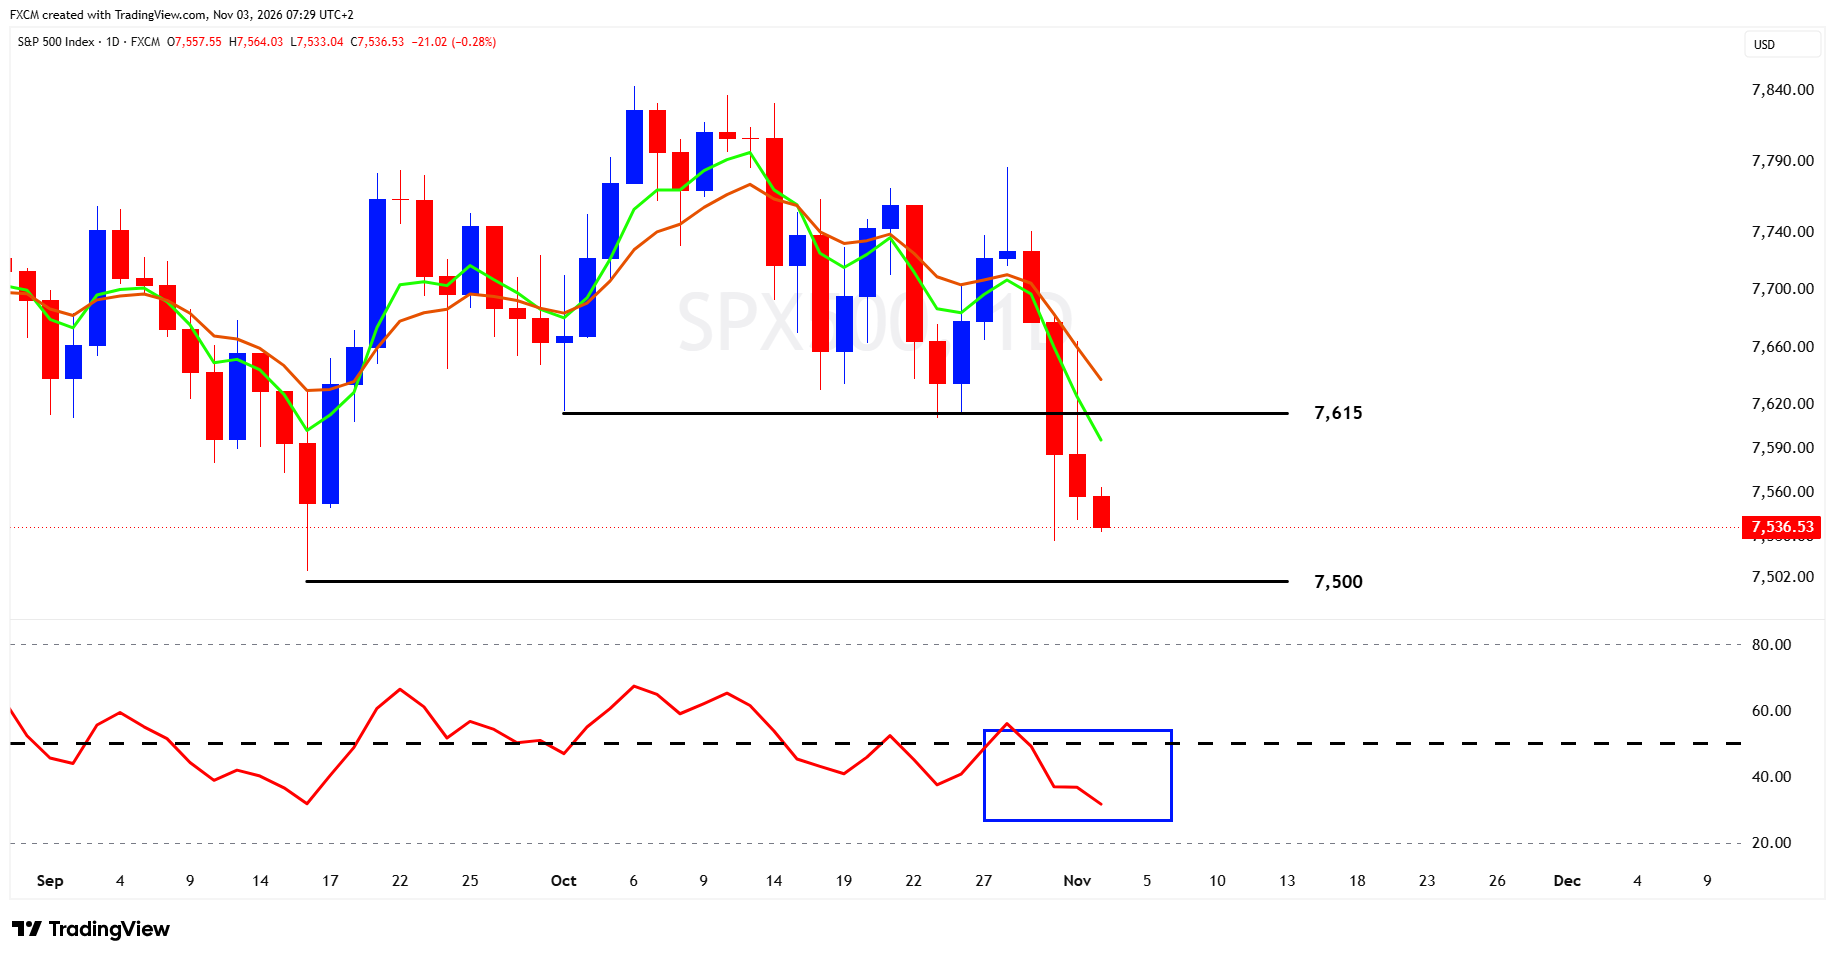
The SPX500 has come under renewed selling pressure, breaking decisively below the important 7,615 support level and reinforcing the increasingly bearish short-term outlook. The index is trading beneath both its short and medium-term moving averages, which are turning lower, while the recent pattern of lower highs points to weakening buying interest. Attention now shifts towards the psychological 7,500 support level, which could prove crucial in determining the next directional move. The RSI has slipped below the neutral 50 threshold and is approaching oversold territory, highlighting deteriorating momentum. As long as the RSI remains below 50, the 7,500 support level is likely to remain under pressure, with a sustained break potentially opening the door to further losses. Conversely, a recovery in the RSI above 50 would suggest improving momentum and could provide the foundation for support to emerge. On the upside, 7,615 now represents an important resistance level, with a sustained recovery above it needed to ease immediate bearish pressure.
Fundamentally, the SPX500 is facing growing pressure as investors reassess the outlook for technology stocks and the enormous sums being committed to artificial intelligence. Recent earnings from Alphabet and Amazon have sharpened concerns about whether the returns on AI investment will justify the spending, triggering renewed selling across heavyweight technology shares. Interest rates are another concern. The Federal Reserve held its benchmark rate at 3.75% to 4.00% in October, but persistent inflation has kept the possibility of further tightening firmly in focus, potentially placing additional pressure on equity valuations. Meanwhile, today's US midterm elections introduce another element of uncertainty, particularly around fiscal policy and regulation. There are reasons for optimism, however. The US economy remains resilient, corporate investment is robust and underlying demand for AI continues to grow. The challenge for equities is that investors are becoming less willing to pay a premium for future growth without clearer evidence of profitability. Until confidence returns to the technology sector and the interest rate outlook becomes more settled, rallies in the SPX500 may struggle to gain lasting traction.
Potential Trade Setups
The SPX500 is facing a critical test as concerns over stretched technology valuations, persistent inflation and uncertainty surrounding the Federal Reserve weigh on investor sentiment. With confidence in the AI investment boom beginning to waver, attention is turning to corporate earnings for clues about where markets head next. Apple's strong results have been overshadowed by margin concerns, while AMD and Qualcomm face important earnings announcements that could set the tone for semiconductor shares. Against this backdrop, weakening technical momentum and key support levels are creating potentially significant trading opportunities, with earnings guidance likely to determine whether buyers regain control or selling pressure intensifies.
Apple (AAPL.us)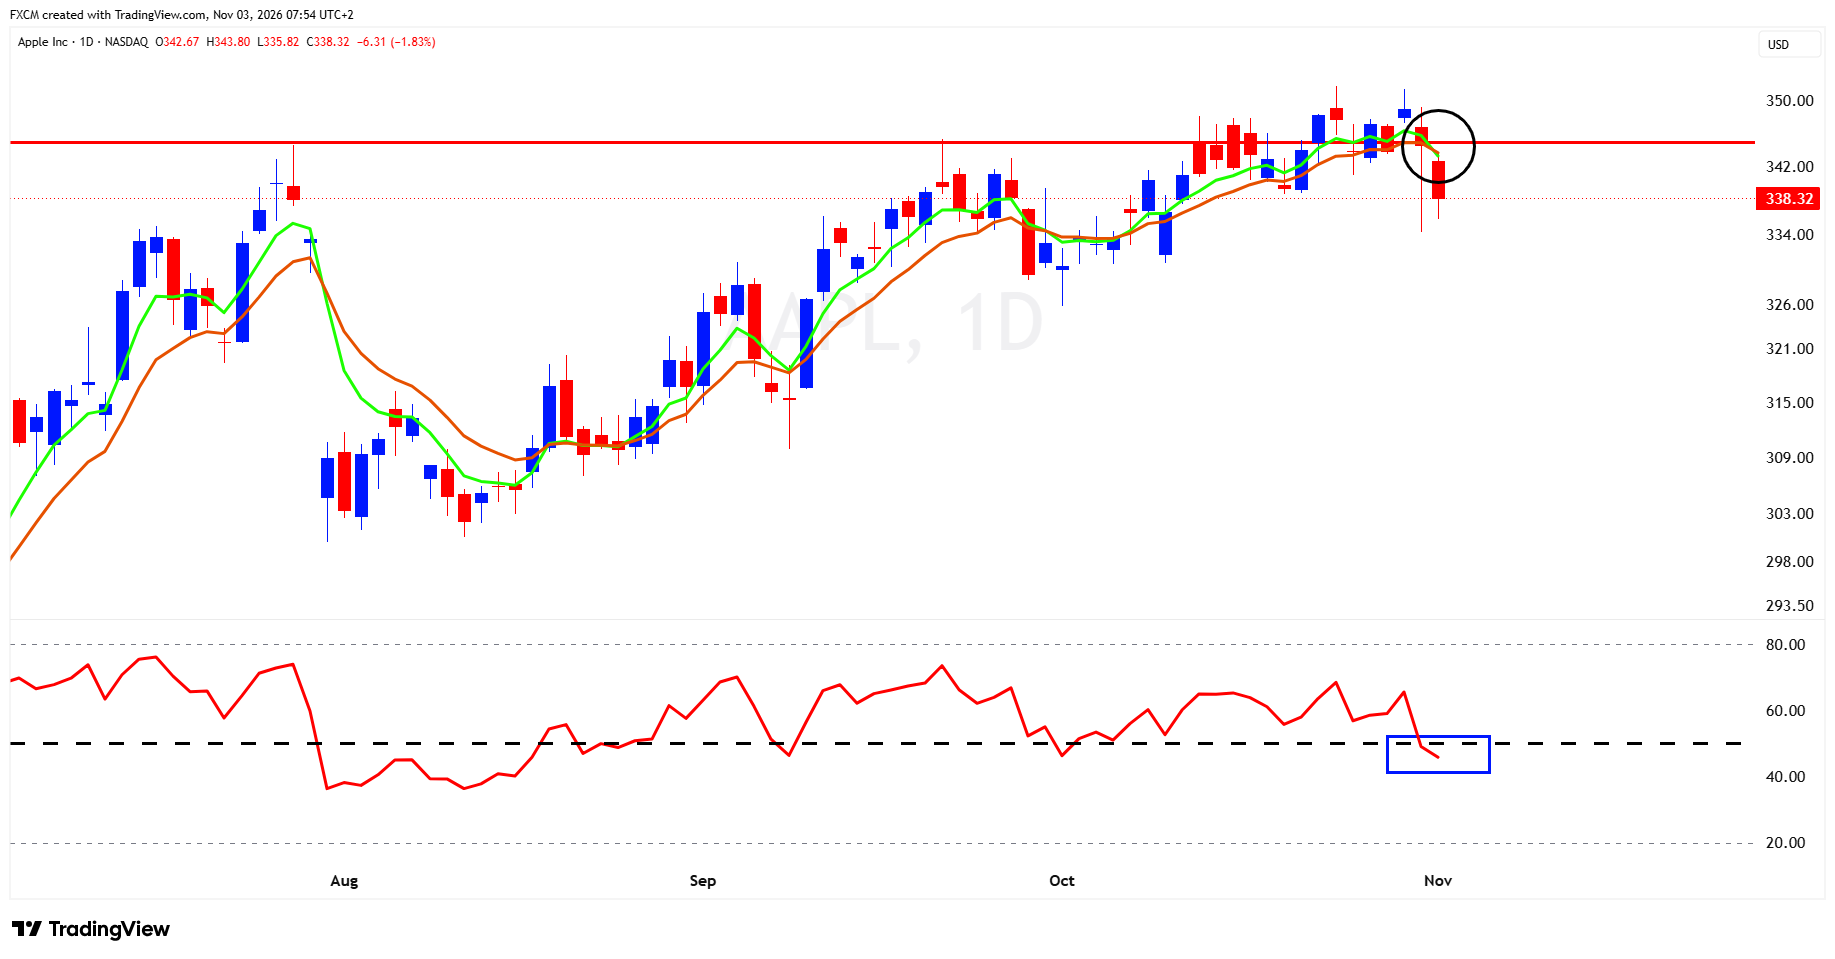
Technical Analysis
Apple has made impressive gains since August, but the $345 resistance area continues to prove a stubborn obstacle, with repeated attempts to establish a meaningful foothold above this level falling short. The latest rejection has pushed the share price back below its short and medium-term exponential moving averages, which are converging and threatening a bearish crossover. Adding to the concern, the RSI has slipped below the neutral 50 threshold, suggesting that buying momentum is fading. If the RSI remains below 50, the $345 resistance level is likely to remain difficult to overcome, potentially exposing the share price to further weakness towards $335, followed by the $330–$326 support region. Conversely, a recovery in the RSI above 50, accompanied by a bullish turn in the EMAs, would suggest renewed buying interest and could set the stage for another challenge of $345. A sustained break above this level would bring the recent highs around $350 back into focus. For now, the broader recovery remains intact, but the near-term technical picture is becoming increasingly fragile.
Fundamental Perspective
Apple's latest earnings delivered a familiar dilemma for investors. The business is performing well, but expectations remain demanding. The company reported record September-quarter revenue of $114.5 billion, up 12% from a year earlier, while earnings per share of $2.10 comfortably exceeded Wall Street's forecast of $1.99. Strong iPhone demand and record Services revenue were encouraging, but the outlook for profitability took some of the shine off an otherwise impressive quarter. Apple expects gross margins to fall from 47.9% to between 45% and 46% in the December quarter, largely reflecting rising memory costs, while additional AI-related expenses are adding to the pressure. The company also expects Services revenue growth to moderate to 8%–9%, below market expectations. Investors were clearly unsettled, with the shares falling approximately 2.8% in after-hours trading following yesterday's announcement. There are positives, however. Apple expects December-quarter revenue to grow between 7% and 10%, suggesting that demand remains resilient heading into the important holiday season. For now, the concern is less about Apple's ability to generate sales and more about how much of that revenue will translate into profit. Until investors gain greater confidence in the margin outlook, the shares may struggle to regain momentum, leaving the $345 resistance area difficult to overcome.
Advanced Micro Devices Inc. (AMD.us)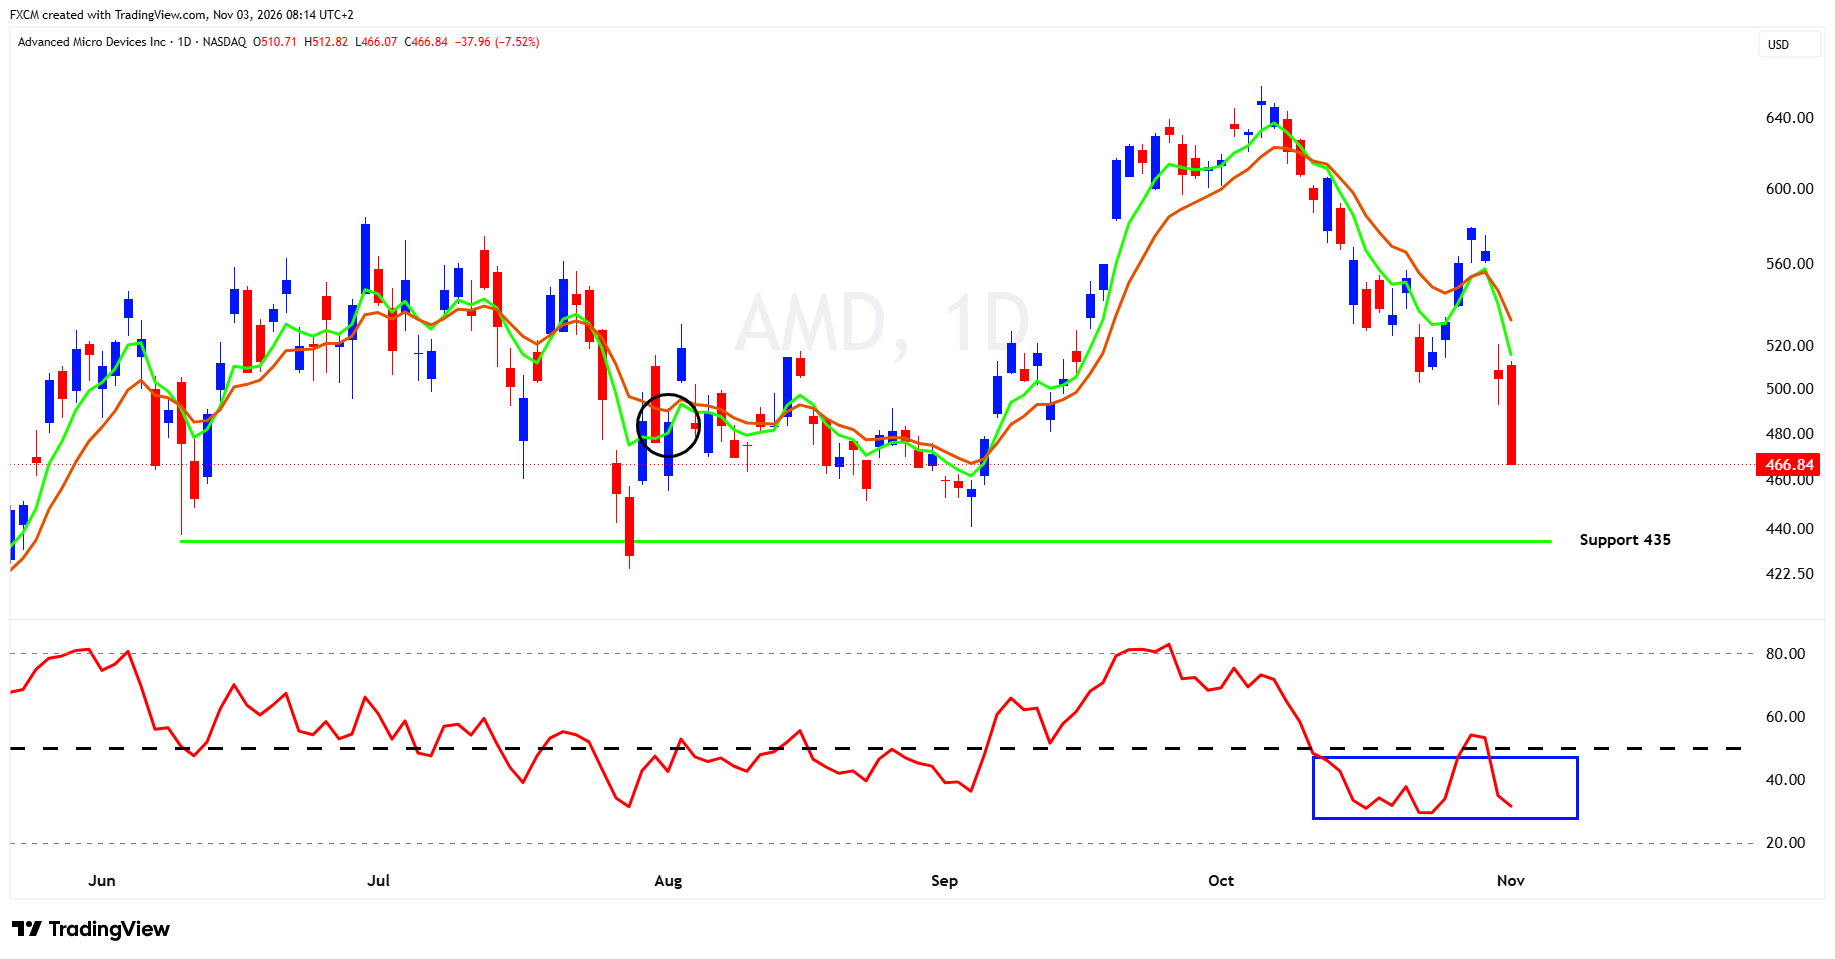
Technical Analysis
AMD is facing mounting selling pressure, with the share price retreating sharply from its October highs and moving towards the important $435 support level. The technical picture has deteriorated considerably, with the short-term exponential moving average trading below its medium-term counterpart, confirming a bearish formation. Adding to the concern, the RSI has struggled to sustain a meaningful recovery above the neutral 50 threshold since early October and has slipped back towards oversold territory. As long as the RSI remains below 50, bearish momentum is likely to dominate, leaving the $435 support level vulnerable to another test. A sustained break below this area could open the door to further losses towards $425. Conversely, should buyers successfully defend $435 and the RSI recover above 50, the shares could begin to offer an attractive technical recovery opportunity. Such a development would improve the prospects of a rebound towards $500. For now, however, the combination of lower highs, weakening momentum and bearish moving averages suggests sellers retain control, particularly ahead of a potentially market-moving earnings announcement.
Fundamental Perspective
AMD faces a crucial test when it releases its third-quarter earnings after the US market closes today. Wall Street expects revenue of approximately $13.1 billion, representing annual growth of nearly 42%, alongside adjusted earnings of around $1.95 per share. These expectations are broadly in line with AMD's own revenue guidance of $13 billion, plus or minus $300 million, and an adjusted gross margin of approximately 56%. However, the headline numbers will tell only part of the story. Investors will be paying particularly close attention to the Data Centre business, where revenue surged 107% to $6.7 billion in the previous quarter, supported by strong demand for EPYC server processors and Instinct AI accelerators. Updates on the commercial adoption of AMD's Helios platform and MI450 accelerators will also be important in assessing the company's ability to compete in the rapidly expanding AI market. Perhaps most crucially, investors will want to see convincing guidance for the December quarter, particularly as concerns about the sustainability of AI spending and weakness in the broader semiconductor sector have unsettled sentiment. Strong results, supported by an encouraging outlook, could help restore confidence and potentially attract buyers around the important $435 technical support level. Conversely, any disappointment in Data Centre growth, profitability or forward guidance could reinforce the prevailing selling pressure and leave the shares vulnerable to further losses.
Qualcomm (QCOM.us)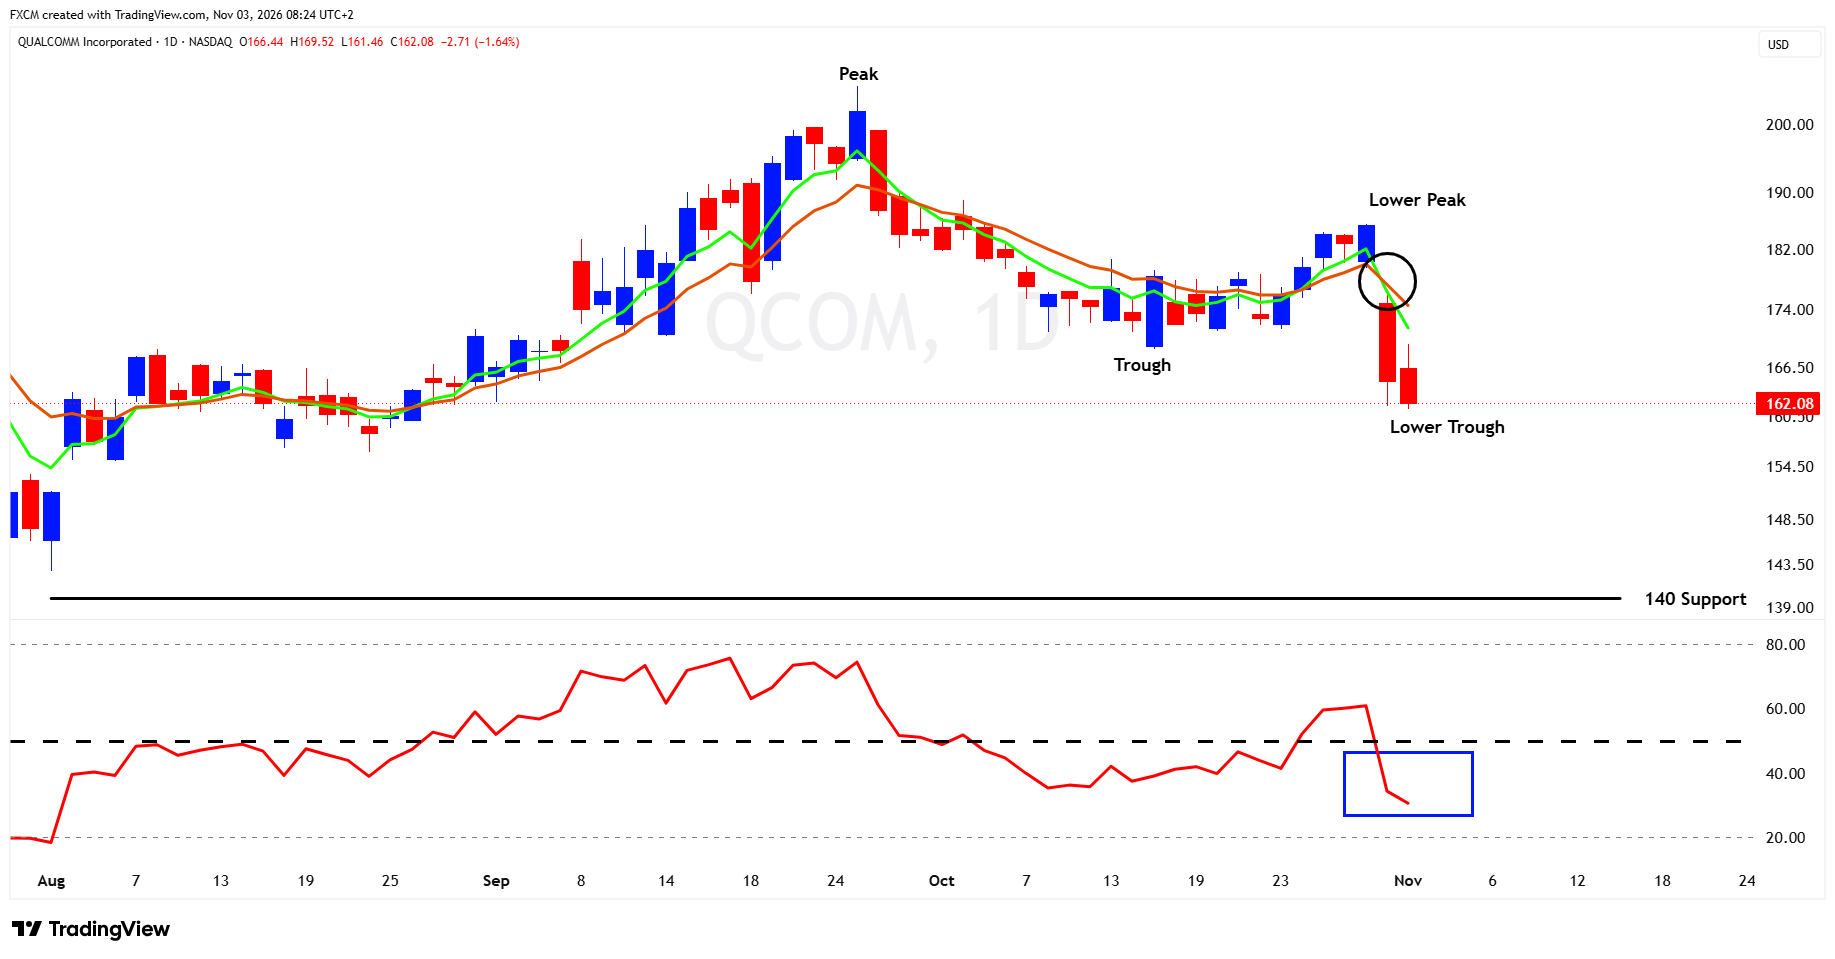
Technical Analysis
Qualcomm has seen its technical outlook deteriorate sharply, with the emergence of a lower peak followed by a lower trough confirming an increasingly bearish price structure. The recent rejection around $185 has accelerated the decline, pushing the shares below both their short and medium-term exponential moving averages, which have crossed into a bearish formation. Adding to the weakness, the RSI has fallen decisively below the neutral 50 threshold, signalling persistent selling momentum. As long as the RSI remains below 50, the share price is likely to remain under pressure, raising the prospect of a move towards the important $140 support level. Conversely, a recovery in the RSI above 50, accompanied by a sustained move back above the declining EMAs, would suggest that selling pressure is easing and could encourage a rebound towards $175–$185. For now, sellers remain firmly in control, with tomorrow's earnings announcement potentially providing the catalyst for the next significant move.
Fundamental Perspective
Qualcomm faces an important test when it reports its fiscal fourth-quarter earnings after the US market closes tomorrow. Wall Street expects revenue of approximately $10.14 billion and adjusted earnings of around $2.16 to $2.17 per share, representing annual declines of roughly 10% and 28%, respectively. These expectations are comfortably within Qualcomm's own guidance, but investors will be looking well beyond the headline figures. The smartphone business remains under pressure from rising memory costs, supply constraints and Apple's gradual transition towards its own modem technology, raising questions about future revenue and profitability. Against this backdrop, Qualcomm's efforts to diversify into automotive technology, Internet of Things applications and AI data centres have become increasingly important. Management expects non-handset revenue growth to accelerate from 24% in fiscal 2026 to more than 60% in fiscal 2027, an ambitious target that investors will be eager to see supported by convincing guidance. Its growing automotive business and recently announced AI infrastructure collaboration with Amazon provide reasons for optimism, although their financial contribution will need to justify expectations. Ultimately, the outlook for fiscal 2027 could matter more than the quarterly results themselves. Strong earnings accompanied by reassuring guidance could help restore confidence and encourage buyers to emerge following the recent sell-off. Conversely, disappointing handset demand, further margin pressure or any indication that diversification is progressing more slowly than anticipated could reinforce the bearish technical picture, potentially bringing the important $140 support level into focus.
Hot News, Cold Logic
US stocks suffered a sharp late-session reversal as another attempted AI rebound faded, pushing the technology sector deeper into correction territory. For investors, the more important signal is the rotation beneath the surface, with most other S&P 500 sectors rising even as tech weakened. With earnings, the midterms and the October jobs report all due this week, the next test is whether tech can reclaim leadership or whether capital continues shifting into cheaper areas of the market.
Final Thought
The market's resilience is being tested, but not yet broken. The sharp retreat in AI shares has exposed growing doubts over the cost and eventual returns of extraordinary investment, yet improving market breadth suggests investors are rotating rather than abandoning equities altogether. With oil still elevated and interest rates likely to remain restrictive, the next leg higher will depend increasingly on earnings strength broadening beyond the technology leaders and on companies proving that ambitious investment can translate into durable cash flows.

Russell Shor
Senior Market Strategist
Russell Shor is a Senior Market Strategist at FXCM, having been promoted to the role in 2025 in recognition of his depth of insight and consistent delivery of high-impact market analysis. He originally joined FXCM in October 2017 as a Senior Market Specialist.
Russell holds an Honours Degree in Economics from the University of South Africa, is a certified FMVA®, and a full member of the Society of Technical Analysts (UK). With over 20 years of experience in financial markets, his work is renowned for its clarity, precision, and strategic value across asset classes.

Any opinions, news, research, analyses, prices, other information, or links to third-party sites contained on this website are provided on an "as-is" basis, as general market commentary and do not constitute investment advice. The market commentary has not been prepared in accordance with legal requirements designed to promote the independence of investment research, and it is therefore not subject to any prohibition on dealing ahead of dissemination. Although this commentary is not produced by an independent source, FXCM takes all sufficient steps to eliminate or prevent any conflicts of interests arising out of the production and dissemination of this communication. The employees of FXCM commit to acting in the clients' best interests and represent their views without misleading, deceiving, or otherwise impairing the clients' ability to make informed investment decisions. For more information about the FXCM's internal organizational and administrative arrangements for the prevention of conflicts, please refer to the Firms' Managing Conflicts Policy. Please ensure that you read and understand our Full Disclaimer and Liability provision concerning the foregoing Information, which can be accessed here.