
RBA raises rates to a 15-year high on persistent inflation


RBA hikes, keeps door open to more
The Reserve Bank of Australia made an aggressive policy pivot earlier this year with three consecutive rate hikes before pausing at the past two meetings. Today, officials unanimously resumed tightening with their fourth 25 basis point increase, bringing interest rates to 4.6% [1] - the highest level since 2011. The swift cumulative tightening of 100 basis points since February may not be enough to restore price stability, however. Policymakers kept the door open to more tightening, reiterating that they will take all necessary action, including "increasing the cash rate target further".
The RBA has strong incentive to stay on track with more tightening and the IMF recently urged it to "remain focused on containing inflation risks" [2]. Officials warned that some of the upside risks to inflation "are materialising" and that firms facing cost pressures are passing them on to consumers or looking to do so. CPI eased to 3.5% y/y in August but remains well above the 2%-3% target, while core inflation persisted at 3.6%.
The Board acknowledged further disruptions to global oil supply since the last meeting, as the Middle East conflict remains unresolved, with USOIL up around 9% this month. Imports of fuels and lubricants rose 42.5% in Q2, driven by higher prices for crude oil and refined petroleum products [3]. At the same time, the AI boom and a severe memory chip shortage are pushing prices of technology-related products higher, exacerbating domestic price pressures.
More tightening has a higher bar
The RBA's forceful policy moves have brought interest rates to the cusp of restrictive territory and financial conditions have tightened, meaning the rate hike runway may be getting shorter. In her press conference, Governor Bullock revealed that policymakers discussed a hold, indicating that further tightening could be more contentious. She also refrained from backing another hike while hinting at a pause to assess incoming data. [4]
Policymakers need to be cautious not to cause unnecessary harm to a fragile economy in their effort to bring down inflation. Growth in consumer spending is already easing while confidence is weak. The Westpac Consumer Confidence index posted a sharp decline of 5.2% in September, marking the first contraction since June [5]. Unemployment is on the rise, hitting 4.6% in August, the highest level in nearly five years. The economy shows resilience with a better-than-projected 2.1% y/y GDP in Q2, but that was the slowest pace since Q1 2025 and the RBA expects growth to slow further through the second half of the year.
AUD/USD drops after the decision
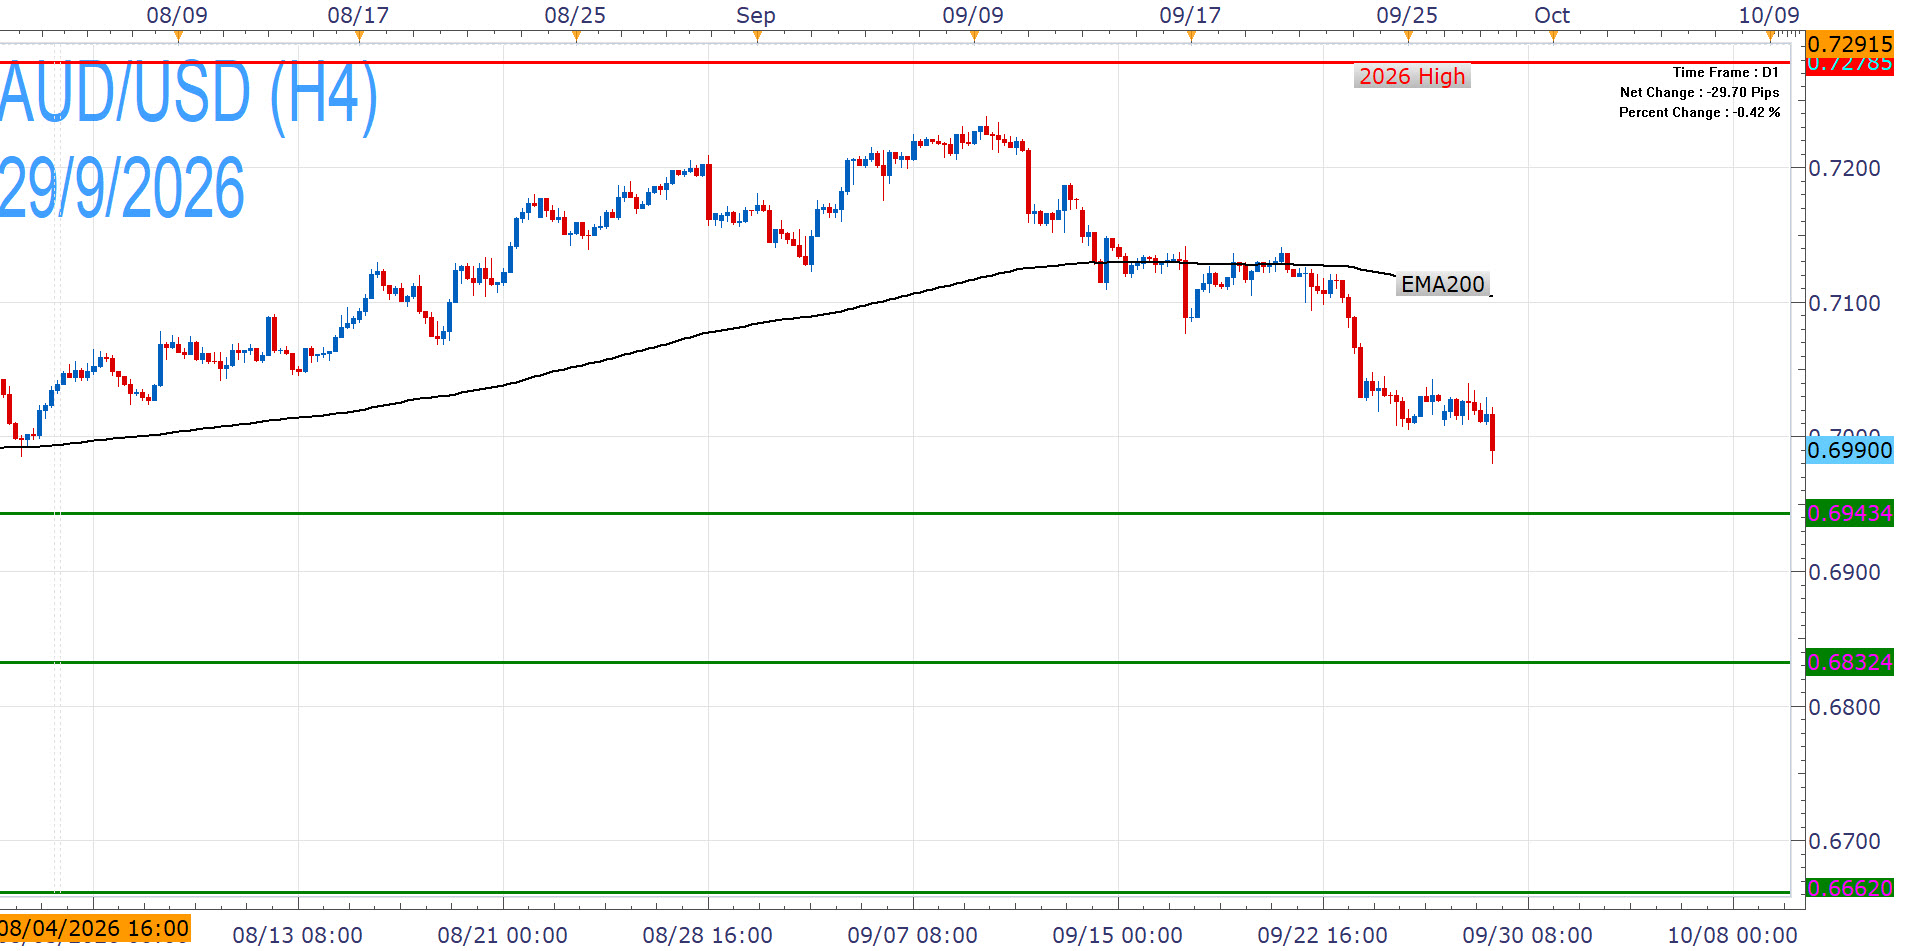
The pair was volatile in the immediate aftermath as markets digested the RBA's aggressive tightening and assessed the path ahead. With oil prices and the AI boom stoking inflationary risks, officials will remain under pressure for additional rate hikes and the next meeting could be a live one. This could support AUD/USD and facilitate a return above the EMA200, reinstating its upside bias.
Despite the initial volatility, AUD/USD extends its monthly losses and is vulnerable to deeper declines. The RBA's frontrunning has likely made policy restrictive, limiting the scope for more tightening, especially as economic headwinds mount.
The pair's trajectory will also depend on the Fed's path and key incoming data from both Australia and the US this week. The Fed pivoted to rate hikes earlier this month and the updated projections showed broad support for another move, a shift that is boosting the USDOLLAR. Incoming communications since then have been on the hawkish side and markets are currently pricing in rate hikes at both remaining meetings of the year.

Nikos Tzabouras
Senior Financial Editorial Writer
Nikos Tzabouras is a graduate of the Department of International & European Economic Studies at the Athens University of Economics and Business. With extensive experience in market analysis and a strong foundation in international relations, he brings a unique perspective to financial markets. Nikos emphasizes not only technical analysis but also on fundamentals and the growing influence of geopolitics on financial trends.
As a Senior Financial Editorial Writer, he delivers comprehensive and forward-looking insights across a wide range of asset classes, including equities, commodities, and currencies. His work explores how macroeconomic events, political developments, and global policies impact market dynamics, providing readers with a deeper understanding of both short-term movements and long-term trends.
References
| Retrieved 29 Sep 2026 https://www.rba.gov.au/media-releases/2026/mr-26-27.html | |
| Retrieved 29 Sep 2026 https://www.imf.org/en/news/articles/2026/09/16/cs-09172026-australia-staff-concluding-statement-2026-aiv-mission | |
| Retrieved 29 Sep 2026 https://www.abs.gov.au/media-centre/media-releases/fuel-and-vehicle-imports-widen-australias-trade-deficit | |
| Retrieved 29 Sep 2026 https://rba.livecrowdevents.tv/MediaConferenceMonetaryPolicyDecision29Sept/stream | |
| Retrieved 03 Nov 2026 https://www.westpaciq.com.au/economics/2026/09/consumer-sentiment-september-2026 |

Any opinions, news, research, analyses, prices, other information, or links to third-party sites contained on this website are provided on an "as-is" basis, as general market commentary and do not constitute investment advice. The market commentary has not been prepared in accordance with legal requirements designed to promote the independence of investment research, and it is therefore not subject to any prohibition on dealing ahead of dissemination. Although this commentary is not produced by an independent source, Friedberg Direct, FXCM or its affiliates takes all sufficient steps to eliminate or prevent any conflicts of interests arising out of the production and dissemination of this communication. The employees of Friedberg Direct and FXCM commit to acting in the clients' best interests and represent their views without misleading, deceiving, or otherwise impairing the clients' ability to make informed investment decisions. For more information about the Friedberg Direct's internal organizational and administrative arrangements for the prevention of conflicts, please refer to the Firms' Managing Conflicts Policy. Please ensure that you read and understand our Full Disclaimer and Liability provision concerning the foregoing Information, which can be accessed here.**