
Bank of Korea hikes again, adding to USD/KRW pressure


BoK delivers hawkish hike
The Bank of Korea raised rates by 25 basis points on Thursday to 3%, the highest level since early 2025. This marked a back-to-back hike following July's pivot, which ended an easing cycle that started more than three years ago and produced 100 basis points of cuts.
Policymakers pointed to further tightening ahead, saying they will determine the "timing and pace of further increases" based on incoming data. Moreover, the updated dot plot creates scope for at least one more hike over the next six months, as ten of 21 dots place rates at 3.25% and six are clustered even higher at 3.5%. [1]
Energy shock and AI boom create need for rate hikes
Both external energy vulnerabilities and domestic tech-driven growth are compounding South Korea's inflation problem, creting the need for additional BoK tightening. The US-Iran conflict and the resulting energy shock have sparked a spike in inflationary pressures, with 70% of South Korea's oil imports sourced from the Middle East[2]. Headline inflation may have eased to 2.8% y/y in July from its two-year-plus peak, but remains well above the central bank's 2% target. With oil prices still elevated, transportation was the biggest contributor with a 7.7% increase. But price pressures go beyond energy, as core CPI continued to rise to 2.6% y/y, the fastest pace since December 2023.
South Korea is an integral part of the global chip supply chain and home to SK Hynix and Samsung - two of only three makers globally of High Bandwidth Memory (HBM). Unprecedented demand is driving investment and exports, leading to strong economic growth. The country's exports continued to rise in July, driven by a 178.8% jump in semiconductors, which exceeded $40 billion for a second straight month. GDP expanded 3.7% y/y in the second quarter and the BoK upgraded its full-year 2026 forecast to 3.3%. [3]
But the AI-fuelled economic expansion is creating demand-side price pressures as it pushes corporate earnings and wages higher. The central bank expects inflation to stay above target for "a considerable time", seeing headline CPI at 2.7% and core at 2.5% for 2026.
A more cautious path may lie ahead
It is clear that the Bank of Korea has a strong incentive to keep tightening, but after raising rates by a cumulative 50 basis points across two consecutive meetings, the cadence could now slow. Today's decision was not unanimous, with one member dissenting in favour of a hold, showing the contours of the BoK's path.
Headline inflation eased in July with oil prices off their peaks, while the recent sharp appreciation of the won against the USDOLLAR could further ease pressures by lowering the cost of imported goods. This could remove some urgency for further hikes, while rising corporate loans and delinquencies [4] offer additional reasons for caution.
At the same time, the economy remains highly dependent on Middle Eastern oil, while the recovery is uneven and heavily concentrated in the tech sector. Geopolitical uncertainty persists, energy flows remain disrupted, risks to AI proliferation linger and concerns over return on investment persist, all of which could contain growth and complicate the central bank's policy path.
USD/KRW slides after BoK hike
USD/KRW faces renewed pressure today following the back-to-back hike by the Bank of Korea, with the pair having declined sharply since July and scope for further weakness both fundamentally and technically. The monetary policy dynamics are unfavourable as the BoK has embarked on a tightening cycle pointing to more hikes ahead, supporting the won. Meanwhile, the USDOLLAR is depreciating due to the Fed's reluctance to hike and fears over ballooning deficits and debt that are eroding confidence. Technically, the formation of a Death Cross, where the EMA50 moves below the EMA200, adds to the downside bias as it is often viewed as a precursor of prolonged declines.
On the other hand, the RSI does not follow prices lower, a divergence that primes USD/KRW for a rebound. Furthermore, won appreciation could ease inflationary pressures and remove urgency for further BoK hikes, while one member already opposed such action today. Meanwhile, markets still expect higher Fed rates this year, which could support the greenback.
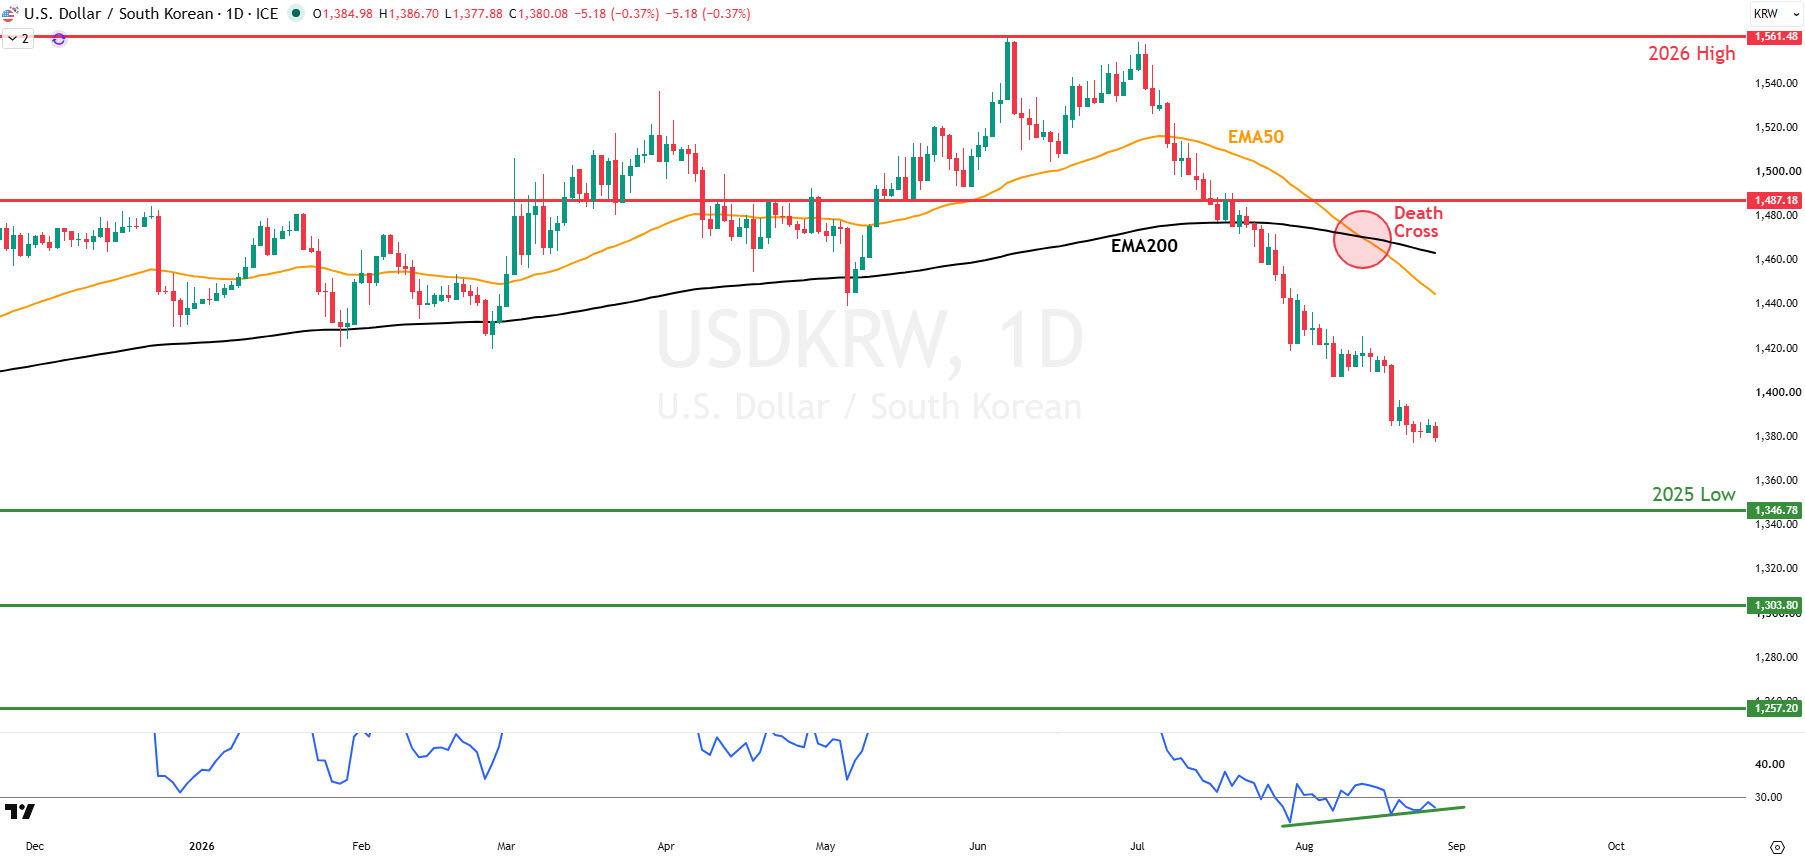
Chart source: www.tradingview.com

Nikos Tzabouras
Senior Financial Editorial Writer
Nikos Tzabouras is a graduate of the Department of International & European Economic Studies at the Athens University of Economics and Business. With extensive experience in market analysis and a strong foundation in international relations, he brings a unique perspective to financial markets. Nikos emphasizes not only technical analysis but also on fundamentals and the growing influence of geopolitics on financial trends.
As a Senior Financial Editorial Writer, he delivers comprehensive and forward-looking insights across a wide range of asset classes, including equities, commodities, and currencies. His work explores how macroeconomic events, political developments, and global policies impact market dynamics, providing readers with a deeper understanding of both short-term movements and long-term trends.
References
| Retrieved 27 Aug 2026 https://www.bok.or.kr/eng/bbs/E0000634/view.do | |
| Retrieved 27 Aug 2026 https://www.kiep.go.kr/gallery.es | |
| Retrieved 27 Aug 2026 https://www.motir.go.kr/kor/article/ATCL3f49a5a8c/172077/view | |
| Retrieved 19 Sep 2026 https://www.bok.or.kr/portal/bbs/P0000593/view.do |

Any opinions, news, research, analyses, prices, other information, or links to third-party sites contained on this website are provided on an "as-is" basis, as general market commentary and do not constitute investment advice. The market commentary has not been prepared in accordance with legal requirements designed to promote the independence of investment research, and it is therefore not subject to any prohibition on dealing ahead of dissemination. Although this commentary is not produced by an independent source, Friedberg Direct, FXCM or its affiliates takes all sufficient steps to eliminate or prevent any conflicts of interests arising out of the production and dissemination of this communication. The employees of Friedberg Direct and FXCM commit to acting in the clients' best interests and represent their views without misleading, deceiving, or otherwise impairing the clients' ability to make informed investment decisions. For more information about the Friedberg Direct's internal organizational and administrative arrangements for the prevention of conflicts, please refer to the Firms' Managing Conflicts Policy. Please ensure that you read and understand our Full Disclaimer and Liability provision concerning the foregoing Information, which can be accessed here.**