
AlphaTrack – Fed Decision and Big Tech Earnings Put SPX500’s Fragile Momentum to the Test

Thoughtful insights and approachable analysis.
- Microsoft eyes a bullish breakout. Could Wednesday's earnings and Azure's AI growth ignite the next rally?
- Google shares under pressure. Can Wednesday's earnings spark a rebound, or is the critical $315 support level about to crack?
- Amazon faces an earnings showdown. Can AWS growth rescue the shares, or is a break below $245 support on the cards?
Quick Market Overview
US stocks opened the week higher as renewed enthusiasm around AI lifted technology shares, but investors now face a crucial test from earnings and the Federal Reserve. With roughly a third of the S&P 500 reporting, guidance from major companies such as Alphabet, Microsoft and Caterpillar will be key to judging whether profit growth can support current valuations. The Fed is expected to hold rates steady, leaving investors focused on any clues about inflation and the likelihood of another hike in December.
General Equity Market Health (SPX500)
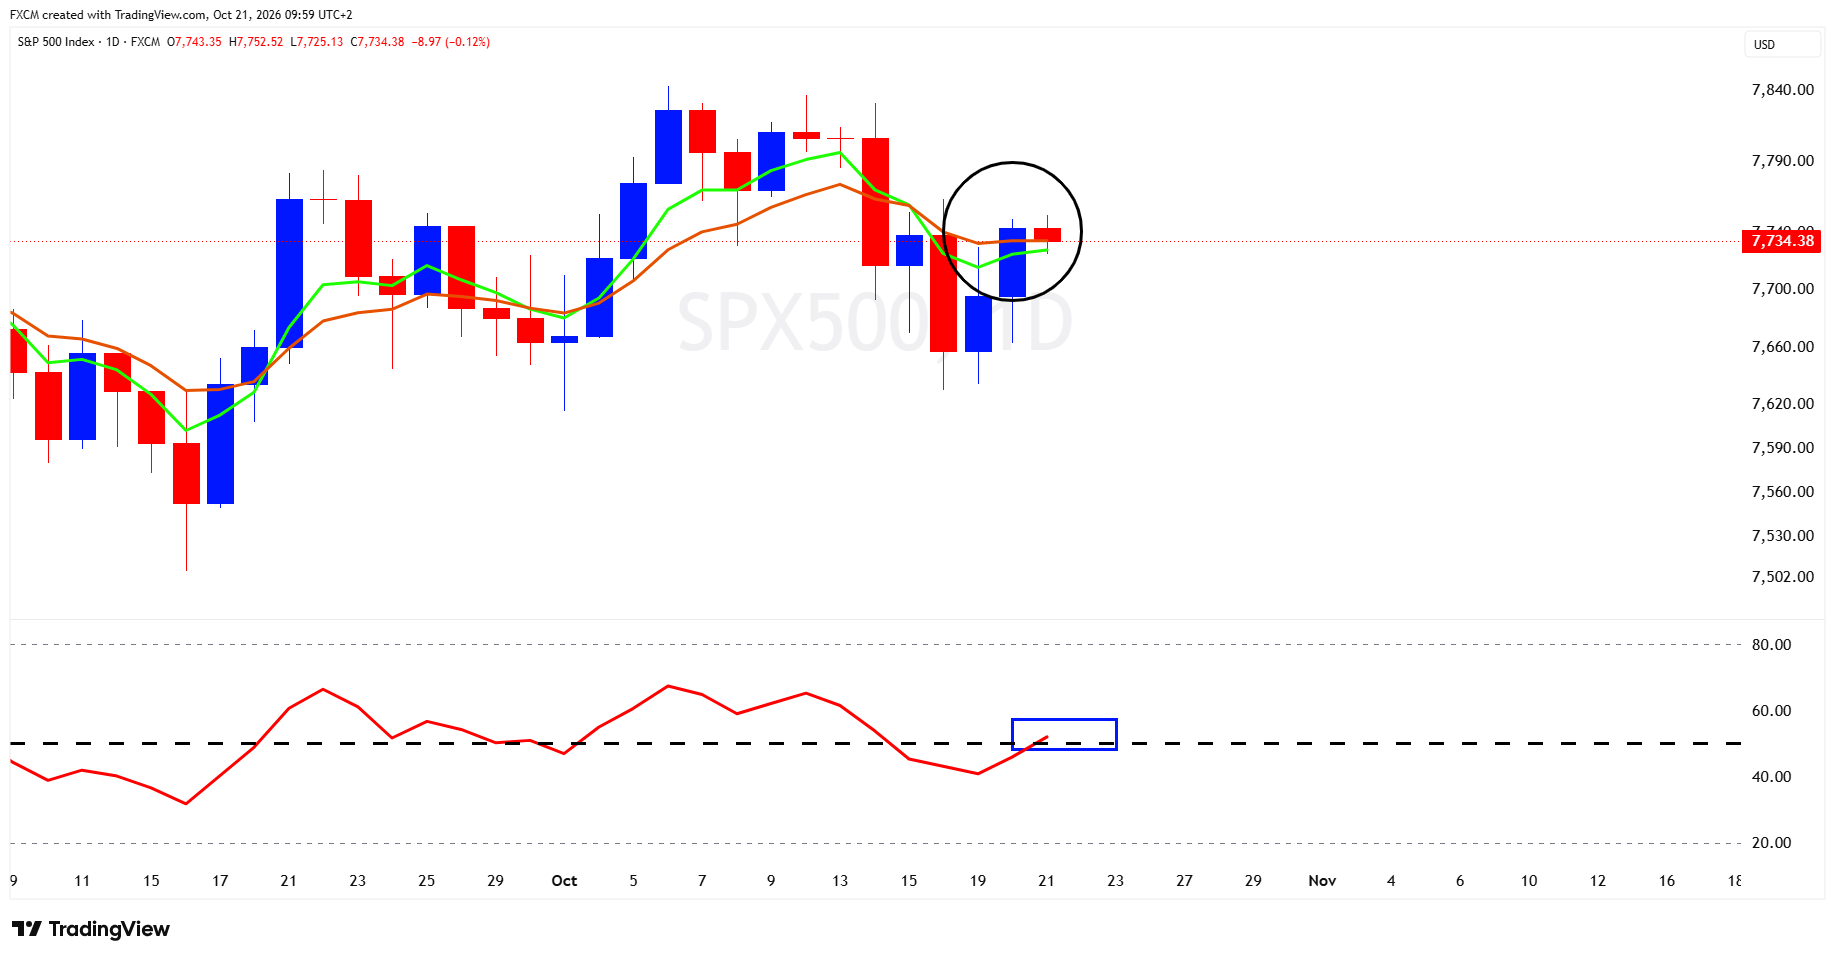
The SPX500 continues to consolidate, although the balance of technical evidence is beginning to tilt towards the bears. The shorter-term exponential moving averages (EMAs) have adopted a bearish formation, but this should not be mistaken for a definitive sell signal. EMAs are inherently trend-following indicators and can generate false signals during periods of sideways trading. More revealing is the Relative Strength Index (RSI), which has slipped below the neutral 50 threshold and has struggled to regain it, suggesting that upside momentum remains fragile. A sustained recovery above 50 would be an encouraging development, potentially supporting a move towards initial resistance around 7,720, followed by the 7,770 region. Conversely, continued failure to reclaim 50 would suggest that selling pressure is likely to build, placing 7,615 firmly in focus as the critical support level. A decisive break below this floor could open the way towards 7,560. For now, the index is neither convincingly bullish nor decisively bearish, but with momentum favouring sellers, the burden of proof increasingly rests with buyers.
The SPX500's hesitant price action comes at a time when investors have plenty to consider, but few easy answers. The Federal Reserve is widely expected to leave interest rates unchanged on Wednesday, although persistent inflation and the possibility of further monetary tightening remain concerns. Adding to the uncertainty is a busy earnings calendar, with Microsoft and Alphabet reporting on Wednesday and Amazon following on Thursday. These results will offer an important test of the enthusiasm surrounding artificial intelligence, particularly whether the enormous sums being invested in AI infrastructure are translating into sustainable earnings growth. Meanwhile, elevated Treasury yields and oil prices, against a backdrop of continuing tensions involving Iran, are keeping inflation and valuation risks firmly in view. None of this necessarily points to a sustained market decline, but it does help explain why investors may be reluctant to chase prices higher without further reassurance. For the SPX500, stronger earnings and a reassuring Fed message could provide the catalyst needed to restore momentum, while disappointment could leave the index vulnerable to another test of support at 7,615.
Potential Trade Setups
With Microsoft, Alphabet and Amazon all approaching key earnings updates, the focus shifts from the broader AI story to how well each company is turning heavy investment into growth, margins and cash flow. The following setups highlight where improving fundamentals and market expectations could create attractive trading opportunities.
Microsoft (MSFT.us)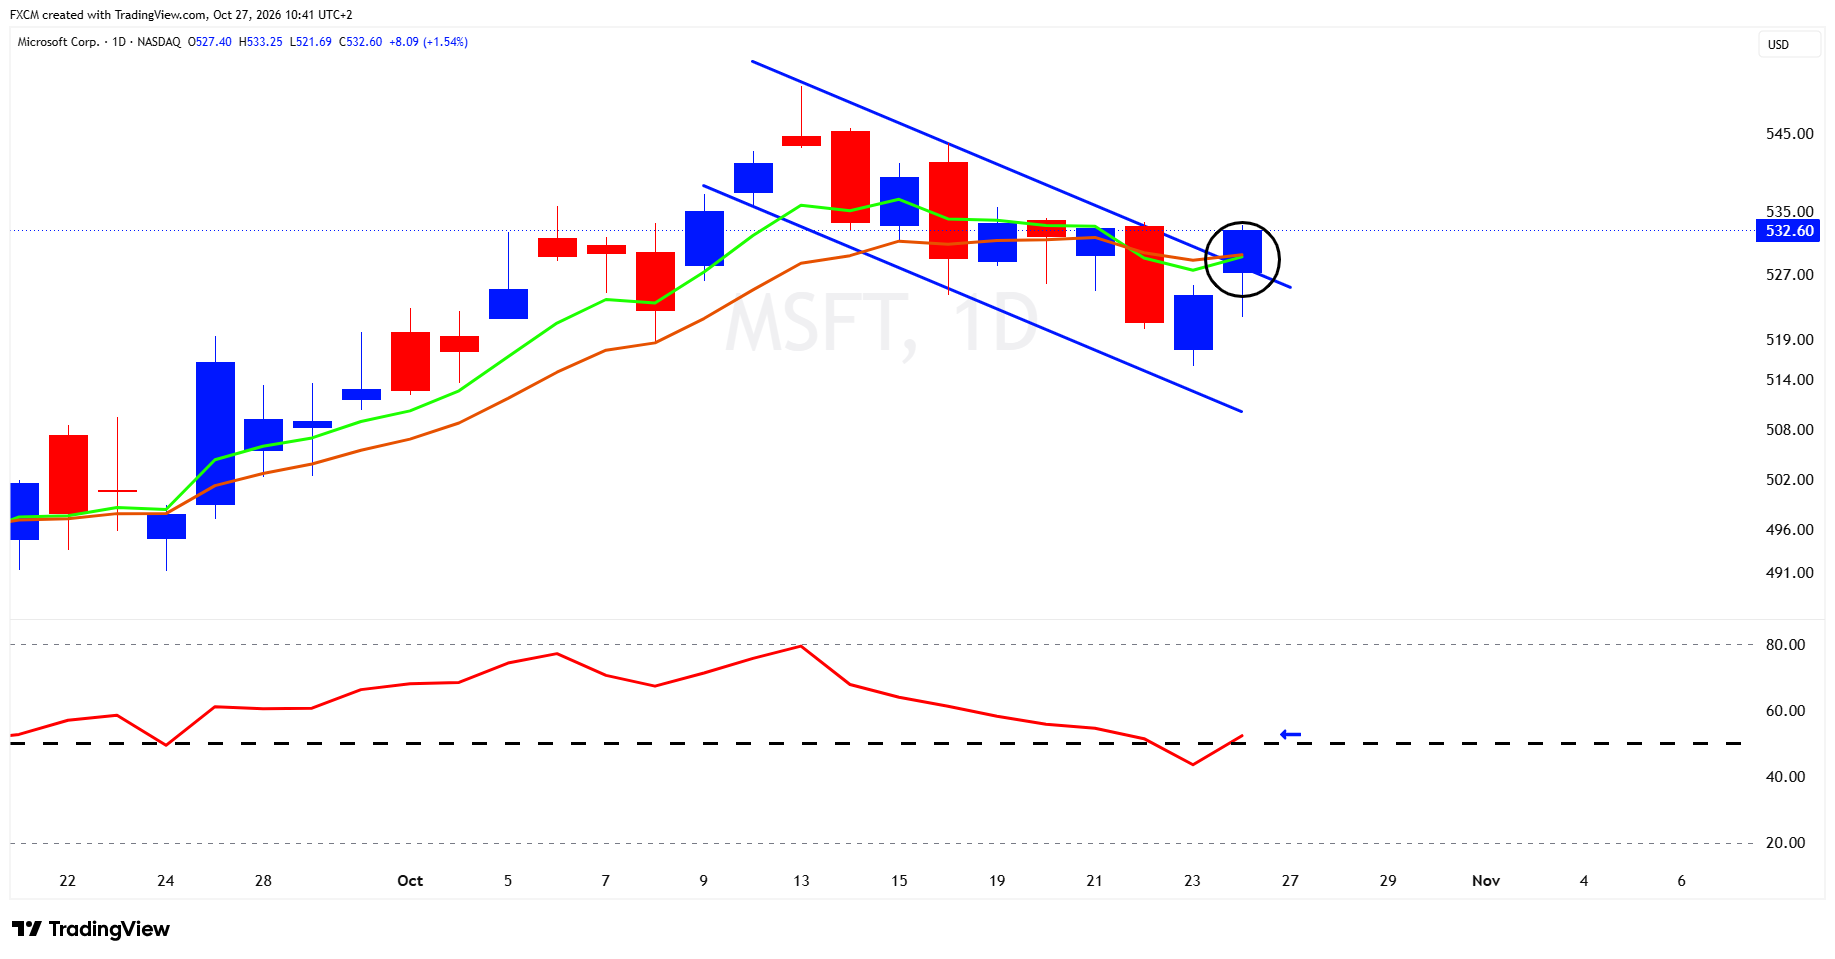
Technical Analysis
Microsoft is showing early signs of potentially breaking out of a bullish flag formation, raising the possibility that its underlying upward trend is preparing to resume. The shares have challenged the upper boundary of the descending channel, although a sustained move above the trendline is still needed to confirm the breakout. Encouragingly, the Relative Strength Index (RSI) has recovered above the neutral 50 threshold, suggesting that positive momentum may be rebuilding. Provided the RSI holds above this level, buyers could gain confidence, potentially opening the way towards initial resistance around $545, followed by the recent highs near $550. The shorter-term exponential moving averages (EMAs) are also converging, with a bullish crossover providing further confirmation that momentum is shifting in favour of buyers. However, with earnings approaching, the emerging breakout faces an important test. Failure to sustain the move above the flag's upper boundary could see the shares retreat towards $520, while a stronger recovery would lend credibility to the bullish technical outlook.
Fundamental Perspective
Microsoft's earnings on Wednesday could prove decisive for the emerging technical breakout. Wall Street is expecting revenue of approximately $90.6 billion and adjusted earnings of around $4.72 per share, but the real focus will be on Azure and the returns Microsoft is generating from its substantial investment in artificial intelligence. The company has guided for Azure revenue growth of 44% to 45% in constant currency, alongside quarterly capital expenditure exceeding $50 billion. Those are demanding numbers, and investors will want to see that growing demand for cloud and AI services is translating into sustainable revenue growth without placing undue pressure on profitability. Management's outlook for the December quarter will be particularly important, offering clues about whether demand is keeping pace with investment. Strong Azure performance, coupled with reassuring guidance, could provide the catalyst for Microsoft to extend its technical breakout. However, softer cloud growth or signs that spending is outpacing commercial returns could quickly dampen enthusiasm. Ultimately, investors will be looking for more than another earnings beat. They will want convincing evidence that Microsoft's enormous AI investment is delivering the growth needed to justify it.
Alphabet (GOOG.us)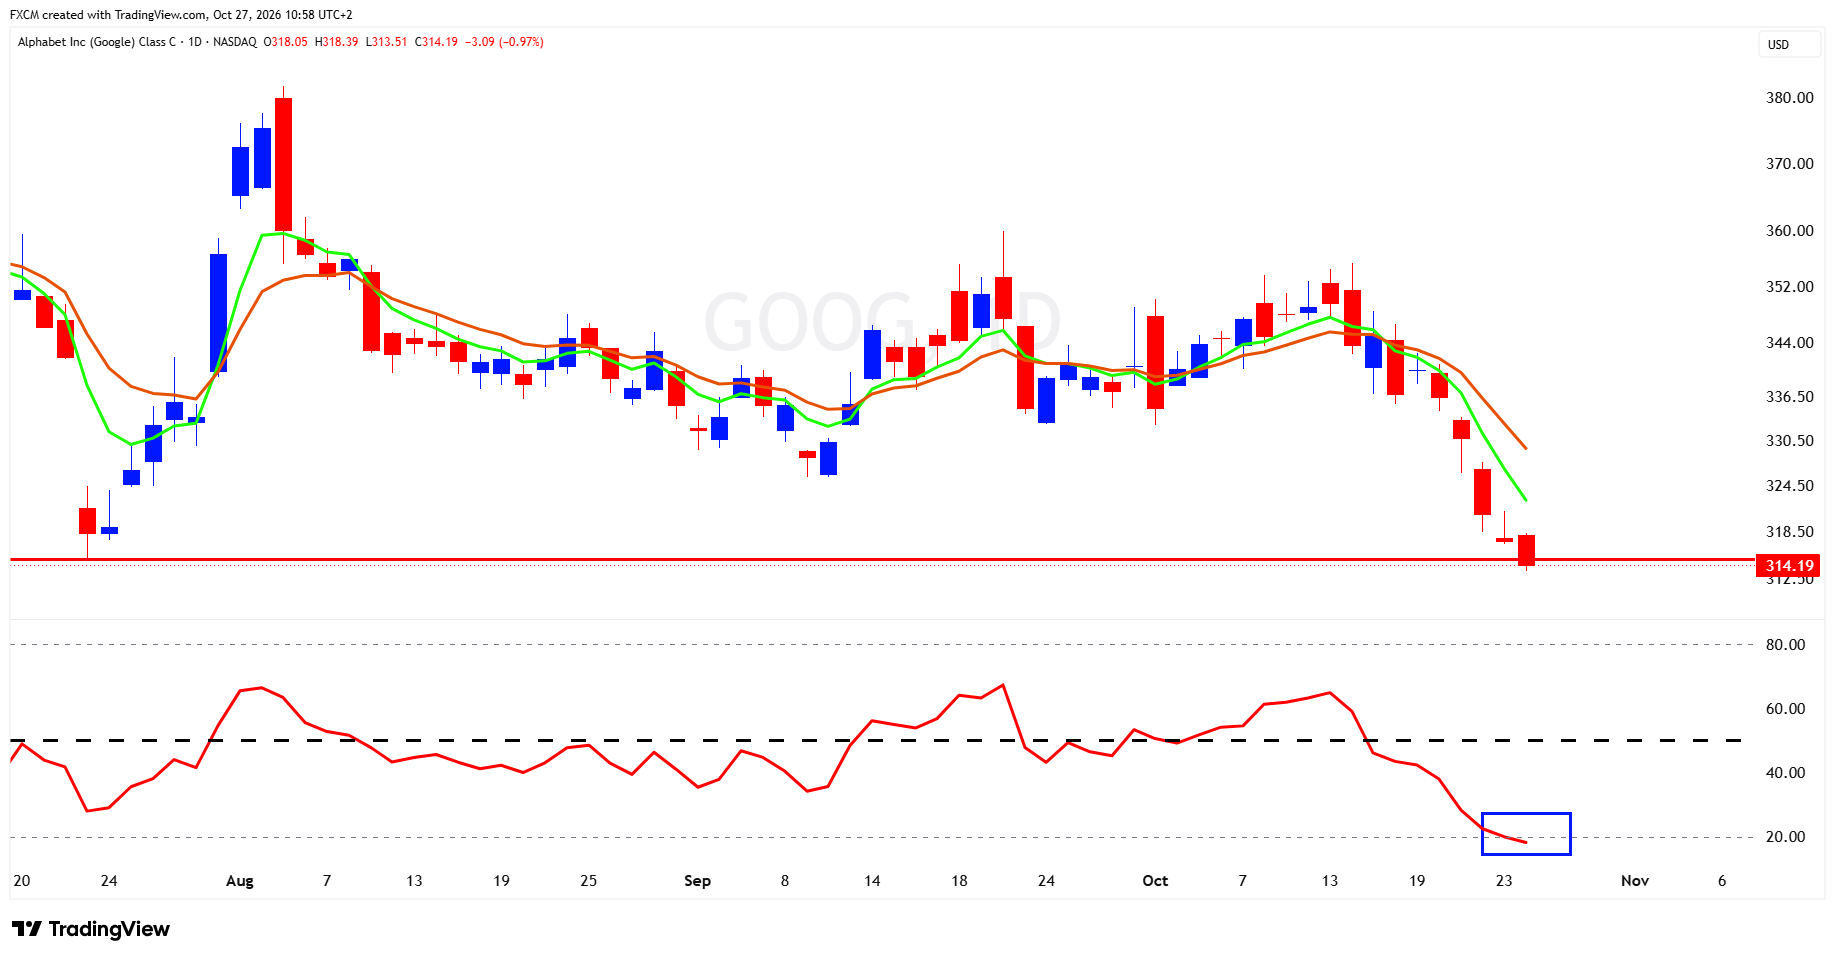
Technical Analysis
Alphabet is firmly on the defensive, with a succession of lower highs and lower lows pointing to sustained selling pressure. The bearish alignment of the exponential moving averages (EMAs), together with price trading beneath both averages, reinforces the negative technical picture. However, the Relative Strength Index (RSI) has slipped deeply into oversold territory, below 20, suggesting that the recent decline may have become overstretched and that a technical rebound is possible. An oversold reading is not, however, a buy signal in itself, particularly when downside momentum remains strong. For a more convincing recovery to develop, the RSI would need to climb back above the neutral 50 threshold and, importantly, hold there. Until then, any rebound risks being little more than a temporary reprieve within the prevailing downtrend. The $315 region is the immediate battleground, with the shares already testing this important support area. A decisive break below it would strengthen the bearish case and potentially expose the psychologically important $300 level. Conversely, a successful defence of $315, accompanied by an improving RSI, could provide the foundation for a recovery towards initial resistance around $324–$330.
Fundamental Perspective
Alphabet's third-quarter earnings, due after the US market closes on Wednesday, arrive with the shares already under considerable pressure. Wall Street expects revenue of approximately $127.9 billion, representing annual growth of around 25%, while earnings forecasts centre on $3.00 per share. However, the bigger question is whether Alphabet's aggressive investment in artificial intelligence is beginning to deliver the returns investors expect. Google Cloud will be closely watched, with Visible Alpha forecasting revenue of approximately $29.2 billion, but growth alone may not be enough to satisfy the market. Investors will also be looking at margins, the resilience of Google's Search advertising business and management's outlook for AI-related demand. Spending is another concern, particularly after Alphabet raised its full-year capital expenditure guidance to between $195 billion and $205 billion. With so much already being invested, the company will need to demonstrate that revenue growth can translate into sustainable profits and cash flow. Strong Cloud performance, resilient advertising revenue and reassuring guidance could provide the spark for a technical recovery. Conversely, disappointing results or signs that costs are rising faster than the benefits of AI investment could deepen the current sell-off. For now, Alphabet faces a straightforward challenge: convincing investors that its ambitious spending plans will deliver worthwhile returns.
Amazon.com (AMZN.us)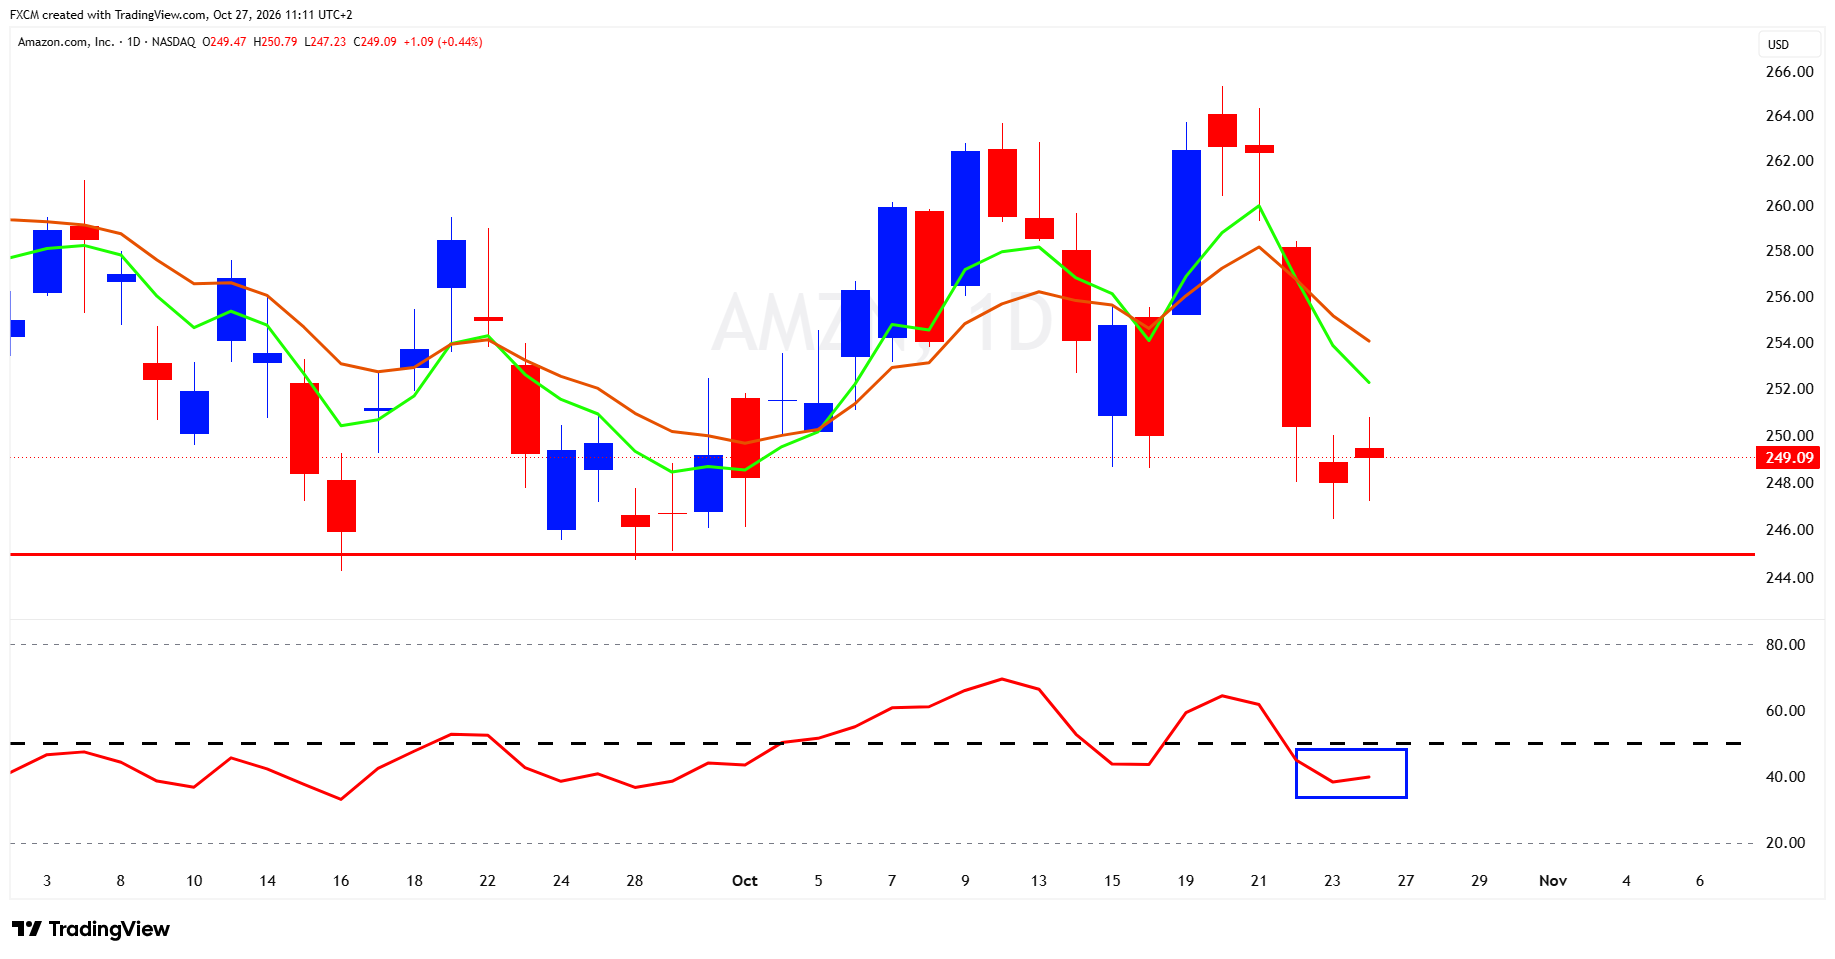
Technical Analysis
Amazon is looking increasingly vulnerable, with the recent retreat from the $264 region leaving the shares under pressure and threatening a test of key support at $245. The technical picture has deteriorated noticeably, with prices slipping beneath both exponential moving averages (EMAs) and the shorter-term average turning below its longer-term counterpart, reinforcing the emerging bearish bias. The Relative Strength Index (RSI) has also fallen below the neutral 50 threshold and is hovering around 40, suggesting that sellers currently have the upper hand. Unless the RSI can recover above 50 and sustain that move, selling pressure could intensify, increasing the likelihood of a break below $245, the critical support level. Such a move would weaken the broader price structure and potentially expose the psychological $240 region. Conversely, a successful defence of $245, accompanied by an improving RSI, could encourage a rebound towards initial resistance around $254–$258. With earnings approaching, however, the immediate direction may depend as much on the company's outlook as on the technical indicators.
Fundamental Perspective
Amazon's third-quarter earnings, due after the US market closes on Thursday, could prove important for shares already struggling to regain their footing. Wall Street expects revenue of approximately $202.2 billion and earnings of around $1.96 per share, although the performance of Amazon Web Services (AWS) is likely to attract particular attention. AWS grew revenue by 37% in the previous quarter, its fastest pace in 18 quarters, and investors will be looking for evidence that this momentum is continuing. The bigger question, however, is whether Amazon's substantial investment in artificial intelligence is generating sufficient returns. Free cash flow has already come under pressure as spending on data centres and other infrastructure accelerates, making profitability and future investment plans especially important. Investors will also be watching the retail and advertising businesses, together with management's guidance for the crucial holiday shopping quarter. Strong AWS growth, healthy operating margins and an encouraging outlook could help restore confidence and support a rebound from the $245 technical support region. Conversely, disappointing cloud growth or further pressure on cash generation could reinforce the recent selling. Ultimately, Amazon needs to show that its ambitious AI expansion can deliver stronger earnings and cash flow, not simply higher spending.
Hot News, Cold Logic
Hedge funds sharply reduced technology exposure during last week's selloff, highlighting weakening conviction in the crowded AI trade even as underlying demand remains strong. For investors, the key question is whether upcoming hyperscaler earnings can justify the scale of AI spending and restore confidence after weeks of de-risking and rising volatility. The bull market can still continue, but with earnings growth slowing in 2027 and macro risks elevated, returns may become more selective, volatile and dependent on stock-specific execution.
Final Thought
Markets are discovering that confidence in AI can recover faster than the questions surrounding how it will ultimately be financed. The technology remains a powerful earnings story, but with capital requirements soaring, oil still above $110 and bond yields hovering near 5%, the hurdle for further gains is becoming increasingly demanding. The broader bull case remains intact, but the next leg higher will depend less on enthusiasm alone and more on Big Tech proving that extraordinary AI investment can translate into durable cash flows while oil and interest rates do not tighten financial conditions further.

Russell Shor
Senior Market Strategist
Russell Shor is a Senior Market Strategist at FXCM, having been promoted to the role in 2025 in recognition of his depth of insight and consistent delivery of high-impact market analysis. He originally joined FXCM in October 2017 as a Senior Market Specialist.
Russell holds an Honours Degree in Economics from the University of South Africa, is a certified FMVA®, and a full member of the Society of Technical Analysts (UK). With over 20 years of experience in financial markets, his work is renowned for its clarity, precision, and strategic value across asset classes.


Any opinions, news, research, analyses, prices, other information, or links to third-party sites contained on this website are provided on an "as-is" basis, as general market commentary and do not constitute investment advice. The market commentary has not been prepared in accordance with legal requirements designed to promote the independence of investment research, and it is therefore not subject to any prohibition on dealing ahead of dissemination. Although this commentary is not produced by an independent source, FXCM takes all sufficient steps to eliminate or prevent any conflicts of interests arising out of the production and dissemination of this communication. The employees of FXCM commit to acting in the clients' best interests and represent their views without misleading, deceiving, or otherwise impairing the clients' ability to make informed investment decisions. For more information about the FXCM's internal organizational and administrative arrangements for the prevention of conflicts, please refer to the Firms' Managing Conflicts Policy. Please ensure that you read and understand our Full Disclaimer and Liability provision concerning the foregoing Information, which can be accessed here.